The Indian two-wheeler market achieved total domestic sales of 24,63,103 units in September 2026, marking a 13.50% rise compared to the 21,70,100 units registered in September 2025. Volumes also advanced by 21.05% against August 2026 figures of 20,34,698 units. Within this ecosystem, the domestic scooter segment touched a record-breaking 9,95,576 units, surging 34.07% from 7,42,602 units a year prior and expanding 16.34% month-on-month from August's 8,55,715 units. Scooters accounted for roughly 86% of the domestic market's overall year-on-year volume expansion, taking up a 40.42% share of September sales while motorcycles held 57.33%.
Top 10 Scooters and Segment Leaders
The top 10 scooter nameplates accumulated collective sales of 8,42,293 units in September 2026, climbing 32.47% and making up roughly 84.60% of the month's overall domestic scooter volumes. The Honda Activa cemented its dominance at the top by recording 3,52,271 units, representing a 48.19% surge over the 2,37,716 units sold in September 2025. This absolute gain of 1,14,555 units contributed to over half of the combined net growth of the top 10 group. The TVS Jupiter secured second position with 1,54,725 units, representing an 8.87% improvement over 1,42,116 units, with Activa and Jupiter combined capturing approximately 60% of the group volume.
Suzuki Access kept its hold on third place by dispatching 71,928 units. Trailing closely, the TVS Ntorq range (incorporating 125 and 150 variants) reached 47,955 units, scaling up 44.24% from 33,246 units. Electric offerings also delivered substantial gains; the TVS iQube reached 45,320 units with a 47.05% increase over 30,820 units, capturing 5.38% of top 10 sales. The Bajaj Chetak followed with 42,394 units, growing 38.73% from 30,558 units. Hero's Destini 125 registered 41,839 units up from 21,754 units, generating a 92.33% growth rate that marked the steepest percentage gain across the top 10 list.
The Honda Dio lineup (110 and 125 models) shifted 29,160 units, advancing 22.37% from 23,829 units. Vida posted 28,862 units, leaping 88.28% from 15,329 units to claim the position of second-fastest-growing nameplate. Suzuki Burgman concluded the top 10 rankings with 27,839 units, dipping 1.47% from 28,254 units. Overall, the collective sales of iQube, Chetak, and Vida touched 1,16,576 units, highlighting the rising adoption of electric models within the top tier.
Top 10 Two-Wheelers and Category Dynamics
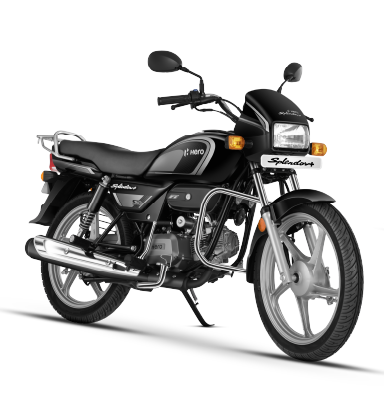
Across the broader two-wheeler industry, the top 10 models together contributed 16,14,472 units, rising 11.97% from the 14,41,876 units recorded in September 2025. Hero Splendor led all two-wheelers with 4,31,279 units, up 12.49% from 3,83,383 units and holding a 26.71% share of the top 10 volume. Honda Shine placed third among all two-wheelers with 1,89,941 units, posting a mild 2.64% increase over 1,85,059 units. Bajaj Pulsar recorded 1,36,313 units, suffering a 12.51% decline from 1,55,798 units—the largest absolute drop of 19,485 units among the top 10.
Hero HF Deluxe secured sixth spot with 1,14,064 units, down 3.37% from 1,18,043 units. TVS Apache registered 61,148 units, expanding 14.67% from 53,326 units. TVS XL moped sales reached 55,517 units, moving up 3.29% from 53,750 units, while the Royal Enfield Classic 350 concluded the top two-wheeler listings with 47,286 units, climbing 16.90% from 40,449 units.
| Nameplate | September 2026 Sales | September 2025 Sales | Growth (%) |
|---|---|---|---|
| Honda Activa | 3,52,271 | 2,37,716 | +48.19% |
| TVS Jupiter | 1,54,725 | 1,42,116 | +8.87% |
| Suzuki Access | 71,928 | 72,238 | -0.43% |
| TVS Ntorq | 47,955 | 33,246 | +44.24% |
| TVS iQube | 45,320 | 30,820 | +47.05% |
| Bajaj Chetak | 42,394 | 30,558 | +38.73% |
| Hero Destini 125 | 41,839 | 21,754 | +92.33% |
| Honda Dio | 29,160 | 23,829 | +22.37% |
| Vida | 28,862 | 15,329 | +88.28% |
| Suzuki Burgman | 27,839 | 28,254 | -1.47% |
Exports and Quarterly Performance
Two-wheeler exports in September 2026 expanded by 26.83% to reach 5,44,797 units compared to 4,29,562 units in September 2025. Motorcycle exports contributed 4,65,163 units with a 24.42% increase, while scooter exports improved by 41.27% to 76,370 units against 54,061 units. Combined domestic sales and exports for the industry hit 30,07,900 units, growing 15.70% year-on-year. Scooter exports alone grew 12.17% over August's 68,085 units, bringing total scooter dispatches including exports to 10,71,946 units.
During the July to September quarter (Q3 CY2026), domestic two-wheeler sales reached 64,21,284 units, marking a 15.05% growth over 55,81,174 units from Q3 CY2025. Quarterly domestic scooter sales stood at 26,49,481 units, up 27.44% from 20,79,054 units. Quarterly scooter exports reached 2,17,620 units, climbing 22.29% from 1,77,957 units, bringing total quarterly scooter volumes to 28,67,101 units. In contrast, domestic motorcycle sales for the quarter rose by 7.40% to 36,19,853 units, demonstrating that while motorcycles maintained larger overall volumes and an export count of 14,31,501 units, scooters expanded at more than double the growth rate driven primarily by domestic demand.
Market Implications
The stellar performance of scooters in September and through Q3 2026 underscores a structural shift in urban and semi-urban commuting preferences across India. With domestic scooter sales expanding at nearly four times the pace of motorcycles, manufacturers are experiencing accelerated volume gains led by robust demand for legacy petrol nameplates like the Honda Activa alongside accelerating adoption of electric options from TVS, Bajaj, and Hero Vida.